
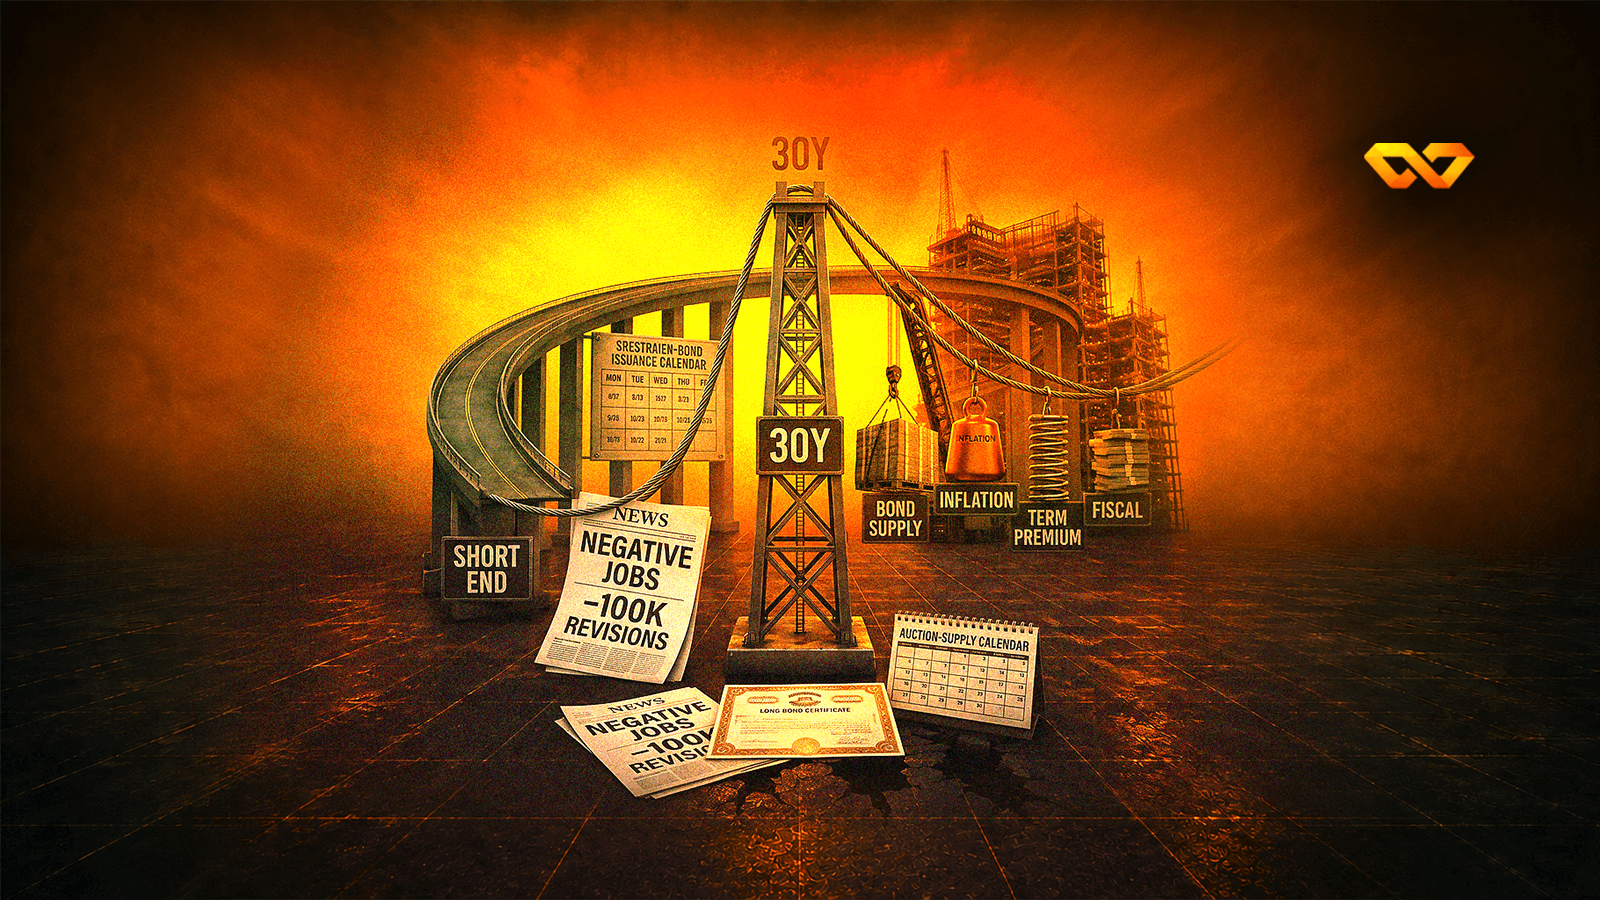
A negative jobs report and downward revisions of one hundred thousand — yet the 30-year yield sits near its highs. This research names every force on each side of the rope and measures them number by number.
Nonfarm Payrolls (NFP) fell by 23 thousand jobs in July, while the May and June readings were revised down by a combined 103 thousand, leaving the three-month average at only +20 thousand. The Yield Curve — the line plotting Treasury yields by maturity — responded on Friday 7 August, the report's release day: the two-year yield fell 6 Basis Points — each point equals 0.01% — the 10-year yield fell 4 points, and the 30-year yield fell 3 points. But by 11 August, the long end had recovered 5 points, with the 30-year yield back at 5.24% — only three basis points below its level on 31 July, before the entire report.
Why did it not fall? Because the long yield is not hostage to jobs alone; it is the result of a tug-of-war between opposing forces: the Real Yield rose 3 basis points between 7 and 11 August, market Breakeven Inflation rose two points, and the Term Premium, through the Kim–Wright model lens, stands at 0.8257%, while fiscal supply injects $739 billion in net private borrowing in Q3 (July–September), according to Treasury estimates. On the deficit side, the shortfall in the first 10 months of fiscal year 2026 reached about $1.798 trillion — or roughly 1.7 trillion after adjusting payment timing — while net interest outlays reached 963 billion, up 14%.
22 August 2026 update — the rope withstood a heavier opponent. In the week after publication, the 30-year yield reached its highest level in nineteen years, prompting the US Treasury on 19 August to double long-term debt buybacks to at least $4 billion per operation from 9 September, with Secretary Scott Bessent saying he was prepared to expand them further. The yield fell 9 basis points to 5.196% that day — then the market fully reversed it over two sessions, closing at 5.273% on 21 August. That is, the long end regained its ground this time not from a jobs report but from the buyer of last resort itself, the strongest test this rope has faced since publication of the report — with the same outcome: the yield returns to where it was.
Verdict: Jobs pulled the curve lower for one day, then four upward forces held the long end. The spread between two years and 30 years widened only from 99 to 102 basis points — limited steepening, not a breakaway. Daily evidence, as we will repeat in every section, establishes coincidence, not standalone causation: we say “is consistent with” and “may contribute”, not “forced the market”.
Positions as of 11 August 2026 • Changes measured from 7 August (jobs-report day), unless otherwise stated
This part of the paper is open to EL7 Pro members and to free members who use one of this month's free papers on it. The paper goes on to analyse the numbers, the causes and what they mean for investors, with tables, charts and sources.
This part of the paper is open to EL7 Pro members and to free members who use one of this month's free papers on it. The paper goes on to analyse the numbers, the causes and what they mean for investors, with tables, charts and sources.
This part of the paper is open to EL7 Pro members and to free members who use one of this month's free papers on it. The paper goes on to analyse the numbers, the causes and what they mean for investors, with tables, charts and sources.
A free account gives you 4 full research papers every month. Or subscribe to EL7 Pro for full access to more than 300 papers.
$700 per year · or $99 per month